Questões de Vestibular Comentadas sobre inglês
Foram encontradas 2.807 questões


By Jeremy Warner
3 Sep 2015
When in trouble, shoot the messenger. This timehonoured approach to dealing with unwelcome news was much in evidence in China this week when nearly 200 people were rounded up and criminally charged with spreading “false" rumours about the stock market and the economy, or otherwise profiting from their travails.
One luckless financial journalist was ritually paraded on state TV, tearfully confessing his “crimes". Meanwhile, the head of the Chinese desk of one London-based hedge fund group was summoned to a “meeting" with regulators, and hasn't been heard of since. Her Chinese husband says “she's gone on holiday". We can only hope it is not to the re-indoctrination of the asbestos mines. Despite the massive progress of recent decades, old habits die hard.
China was meant to have embraced free market reform, yet these latest actions suggest an altogether different approach. Roughly summarised, it amounts to: “Reform good, but woe betide the free market if it doesn't do what the high command wants it to." When the stock market was going up, the Chinese authorities were perfectly happy to tolerate what, to virtually all Western observers, looked like a dangerously speculative bubble, vaingloriously believing it to be a fair reflection of the wondrous successes of the Chinese economy.
The first rule of stock market investment – that share prices can go down as well as up – seems to have been almost wholly forgotten in the scramble for instant riches. When, inevitably, the stock market crashed, the authorities threw the kitchen sink at the problem, but they failed to halt the carnage. This was an even ruder awakening – for it demonstrated to an already disillusioned public that policy-makers were no longer in control of events. Perhaps they hadn't noticed, but there are today more Chinese with stock trading accounts – some 90 million – than there are members of the Communist Party – “just" 80 million. In any case, powerless before the storm, the authorities have instead turned to scapegoating.
Apparently more liberal, advanced economies, it ought to be said, are by no means averse to this kind of behaviour either. A few years back, Italian prosecutors charged nine employees of Standard & Poor's and Fitch Rating with market abuse for daring to downgrade Italy's credit rating, while it is still commonplace in France to blame Anglo-Saxon speculators and their cronies in the London press for any financial or economic setback.
Nor are Western governments and central bankers averse to a little market manipulation when it suits them. What is “quantitative easing" other than money printing to prop up asset prices, including stocks and shares? Chinese refusal to accept the judgments of “Mr Market", it might be argued, is just a more extreme version of the same thing. Small wonder that European officials sometimes look longingly across at the state-directed capitalism practised in China, and pronounce it a model we might perhaps aspire to ourselves.
As recent events have demonstrated, we should not. China's stock market crash is not the work of malicious financial journalists and short-selling hedge funds, but a signal of difficult time ahead and perhaps even of an economic roadcrash to come. After nearly 35 years of spectacular progress, the Chinese economy faces multiple challenges on many fronts which are not going to be solved by denying harsh realities and imprisoning journalists.
The progress of recent decades belies an industrial sector which in truth has become quite seriously uncompetitive by international standards. Many of China's factories need completely retooling to keep up with developments in robotics and other forms of mechanisation. Yet if industry is to get less labour intensive, this only further steepens the challenge of employment creation.
It is reckoned that China needs to create some 20 million jobs a year just to keep pace with employment demand as the population shifts from land to town, eight million of them in high-end professions to cater for the country's burgeoning output of graduates. China's modernisation has created a monster which it is struggling to feed.
As the export-growth story waned, China compensated by unleashing a massive investment boom, which internal demand is now struggling to keep up with, rendering many of the country's shiny new constructs uneconomic and overburdened with bad debts.
The Chinese leadership looks to growth in consumption and service industries to plug the gap, but these new sources of demand can't do so without further free-market reform, which in turn requires further loosening of the shackles of political control. Without growth, the Communist Party loses its political legitimacy, yet the old growth model is broken, and to achieve a new one, the authorities must cede the very power and influence that sustains them. Rumour-mongering journalists and short-selling speculators can only be blamed for so long.
(http://www.telegraph.co.uk. Adapted)
by Julia Leite and Paula Sambo
August 26, 2015
Not long ago, Brazil's real-estate market was one of the biggest symbols of the country's burgeoning economic might. Now, it's fallen victim to an ever-deepening recession.
PDG Realty SA, once the largest homebuilder by revenue, hired Rothschild last week to help restructure 5.8 billion reais ($1.6 billion) of debt after second-quarter net sales sank 88 percent. Earlier this month, Rossi Residencial SA, which has 2.5 billion reais in debt, also brought in advisers to “restructure operations and review strategies." Since 2010, the builder has lost 99 percent of its stock-market value.
The real-estate industry, which is equal to about 10 percent of Brazil's economy, is emerging as one of the latest casualties of a recession that analysts forecast will be its longest since the 1930s. To make matters worse, interest rates are the highest in almost a decade while inflation is soaring. “There is no real estate company that survives without sales," Bruno Mendonça Lima de Carvalho, the head of fixed income at Guide Investimentos SA, said from Sao Paulo. “You can't import or export apartments. You're relying solely on domestic activity."
PDG tried to boost revenue by lowering prices, financing up to 20 percent of some home purchases and even offering to buy back apartments if banks deny financing. Still, it sold just 217 units in the second quarter on a net basis, compared with 1,749 in 2014.
Negative Outlook
On Friday, Moody's Investors Service cut PDG's rating three levels to Caa3, citing the possibility of significant losses for bondholders and other lenders. Secured creditors may recover less than 80 percent in a default, according to Moody's, which kept a negative outlook on the rating. “The company is facing additional liquidity pressures from a prolonged deterioration in industry dynamics, including weak sales speed, tight financing availability and declining real estate prices," Moody's said.
Sao Paulo-based Rossi said in an e-mailed response to questions that second quarter sales improved and that the company's main focus is to reduce debt. Gross debt fell about 30 percent in the 12 months ended in June, Rossi said.
Home sales in Latin America's biggest economy tumbled 14 percent in the first half of 2015, according to data from the national real estate institute. Builders cut new projects by 20 percent during that span, while available financing shrank by about a quarter.
Real's Collapse
That's a reversal from just two years ago, when realestate prices in places like Rio de Janeiro and Sao Paulo had surged as much as 230 percent as rising incomes, a soaring real and record-low borrowing costs ignited a wave of home buying.
Brazilians find themselves in drastically different circumstances today. The currency fell 0.4 percent Wednesday as of 3:25 p.m. in New York, extending its loss this year to 26 percent. The jobless rate climbed to a five-year high of 7.5 percent last month.
The central bank boosted its key rate to 14.25 percent in July, making it ever more expensive to finance the purchase of a home. “It's a matter of demand, and demand is really weak," Will Landers, who manages Latin American stocks at BlackRock, said from Princeton, New Jersey. “We may have reached a peak in interest rates, but they should continue to be at these levels for a while. Consumers will stay on the sidelines because debt levels are still high, and employment will get worse."
(Business Week at www.bloomberg.com/news. Adapted)
GM wheat no more
pest-resistant than ordinary crops, trial shows
GM wheat designed to repel aphids is no more effective at repelling the bugs than standard varieties a major field trial has revealed

Ian Sample
June 25, 2015
A major field trial of GM wheat that is designed to repel aphids (small insects) has found the crop is no better protected against the pests than conventional wheat. The results come from two years of trials that compared aphid attacks on standard wheat plants with those suffered by a GM version modified to release a natural aphid repellent.
Scientists created the GM wheat strain in the hope that it would deter aphids, which devour the crops and can leave them with infections. They modified the wheat to produce a natural pheromone which aphids release when under attack from predators. The “aphid alarm” makes the bugs flee to safety. Aphids are not the only organisms that release the odour though. More than 400 plants have evolved to secrete the same substance, called E-betafarnesene, or EBF, including peppermint. The chemical doubles up as an attractant for some insects that kill aphids, such as parasitic wasps.
Prior to the field trial, lab tests at Rothamsted found that the pheromone worked as a highly-effective aphid repellent. The work bolstered researchers’ hopes that the trial would demonstrate the crop’s resilience against aphids in the wild. An aphid-resistant wheat crop could have huge benefits for farmers and the environment because the plants would no longer need to be sprayed with insecticides.
“The disappointing thing is that when we tested it in the field, we didn’t find any significant reduction in aphid settlement in the test plots,” said Toby Bruce, who worked on the trial. Details of the trial are published in the journal Scientific Reports.
(www.theguardian.com. Adaptado.)
GM wheat no more
pest-resistant than ordinary crops, trial shows
GM wheat designed to repel aphids is no more effective at repelling the bugs than standard varieties a major field trial has revealed
Ian Sample
June 25, 2015
A major field trial of GM wheat that is designed to repel aphids (small insects) has found the crop is no better protected against the pests than conventional wheat. The results come from two years of trials that compared aphid attacks on standard wheat plants with those suffered by a GM version modified to release a natural aphid repellent.
Scientists created the GM wheat strain in the hope that it would deter aphids, which devour the crops and can leave them with infections. They modified the wheat to produce a natural pheromone which aphids release when under attack from predators. The “aphid alarm” makes the bugs flee to safety. Aphids are not the only organisms that release the odour though. More than 400 plants have evolved to secrete the same substance, called E-betafarnesene, or EBF, including peppermint. The chemical doubles up as an attractant for some insects that kill aphids, such as parasitic wasps.
Prior to the field trial, lab tests at Rothamsted found that the pheromone worked as a highly-effective aphid repellent. The work bolstered researchers’ hopes that the trial would demonstrate the crop’s resilience against aphids in the wild. An aphid-resistant wheat crop could have huge benefits for farmers and the environment because the plants would no longer need to be sprayed with insecticides.
“The disappointing thing is that when we tested it in the field, we didn’t find any significant reduction in aphid settlement in the test plots,” said Toby Bruce, who worked on the trial. Details of the trial are published in the journal Scientific Reports.
(www.theguardian.com. Adaptado.)
Genetically modified foods
Genetically modified (GM) foods are foods derived from organisms whose genetic material (DNA) has been modified in a way that does not occur naturally, e.g. through the introduction of a gene from a different organism. Currently available GM foods stem mostly from plants, but in the future foods derived from GM microorganisms or GM animals are likely to be introduced on the market. Most existing genetically modified crops have been developed to improve yield, through the introduction of resistance to plant diseases or of increased tolerance of herbicides.
In the future, genetic modification could be aimed at altering the nutrient content of food, reducing its allergenic potential, or improving the efficiency of food production systems. All GM foods should be assessed before being allowed on the market. FAO/WHO Codex guidelines exist for risk analysis of GM food.
(www.who.int)
Examine o quadrinho para responder à questão.

Examine o quadrinho para responder à questão.
Examine o cartum.
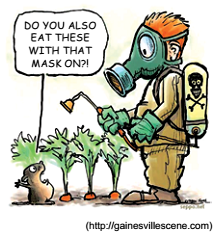
The cartoon means that
TEXTO 8
CAPÍTULO IV
Este Quincas Borba, se acaso me fizeste o favor de ler as Memórias póstumas de Brás Cubas, é aquele mesmo náufrago da existência, que ali aparece, mendigo, herdeiro inopinado, e inventor de uma filosofia. Aqui o tens agora em Barbacena. Logo que chegou, enamorou-se de uma viúva, senhora de condição mediana e parcos meios de vida; mas, tão acanhada, que os suspiros no namorado ficavam sem eco. Chamava-se Maria da Piedade. Um irmão dela, que é o presente Rubião, fez todo o possível para casá-los. Piedade resistiu, um pleuris a levou.
Foi esse trechozinho de romance que ligou os dois homens. Saberia Rubião que o nosso Quincas Borba trazia aquele grãozinho de sandice, que um médico supôs achar-lhe? Seguramente, não; tinha-o por homem esquisito. É, todavia, certo que o grãozinho não se despegou do cérebro de Quincas Borba, — nem antes, nem depois da moléstia que lentamente o comeu. Quincas Borba tivera ali alguns parentes, mortos já agora em 1867; o último foi o tio que o deixou por herdeiro de seus bens. Rubião ficou sendo o único amigo do filósofo. Regia então uma escola de meninos, que fechou para tratar do enfermo. Antes de professor, metera ombros a algumas empresas, que foram a pique.
Durou o cargo de enfermeiro mais de cinco meses, perto de seis. Era real o desvelo de Rubião, paciente, risonho, múltiplo, ouvindo as ordens do médico, dando os remédios às horas marcadas, saindo a passeio com o doente, sem esquecer nada, nem o serviço da casa, nem a leitura dos jornais, logo que chegava a mala da Corte ou a de Ouro Preto.
— Tu és bom, Rubião, suspirava Quincas Borba.
— Grande façanha! Como se você fosse mau!
A opinião ostensiva do médico era que a doença do Quincas Borba iria saindo devagar. Um dia, o nosso Rubião, acompanhando o médico até à porta da rua, perguntou-lhe qual era o verdadeiro estado do amigo. Ouviu que estava perdido, completamente perdido; mas, que o fosse animando. Para que tornar-lhe a morte mais aflitiva pela certeza...?
— Lá isso, não, atalhou Rubião; para ele, morrer é negócio fácil. Nunca leu um livro que ele escreveu, há anos, não sei que negócio de filosofia...
— Não; mas filosofia é uma coisa, e morrer de verdade é outra; adeus.
(ASSIS, Machado de. Quincas Borba. São Paulo: Ática, 2011. p. 23-24.)
In Text 8, most of the verbs in Portuguese are conjugated in the past tense, such as “chegou”, “enamorou-se” e “resistiu”. Complete the following text using the correct past tense conjugation of the verbs in parenthesis in English:
Last night Susan (go) ____________ to her friend’s birthday party. She (dance) ____________ with her boyfriend, and (eat) ____________ cake. After they (leave) ____________ the party, Susan and her boyfriend (decide) ____________ to go and watch a movie at the theater. They (see) ____________ the new Transformer’s movie, and then they went home. When she (get) ____________ home, Susan (take) ____________ a shower and (fall) ____________ asleep quickly.
Choose the correct option from the ones listed below:
TEXTO 7
Memórias de um pesquisador
Não era bem vida, era uma modorra – mas de qualquer modo suportável e até agradável. Terminou bruscamente, porém, eu estando com vinte e oito anos e um pequeno bujão de gás explodindo mesmo à minha frente, no laboratório de eletrônica em que trabalhava, como auxiliar. Me levaram às pressas para o hospital, os médicos duvidando que eu escapasse. Escapei, mas não sem danos. Perdi todos os dedos da mão esquerda e três (sobraram o polegar e o mínimo) da direita. Além disso fiquei com o rosto seriamente queimado. Eu já não era bonito antes, mas o resultado final – mesmo depois das operações plásticas – não era agradável de se olhar. Deus, não era nada agradável.
No entanto, nos primeiros meses após o acidente eu não via motivos para estar triste. Aposentei-me com um bom salário. Minha velha tia, com quem eu morava, desvelava-se em cuidados. Preparava os pastéis de que eu mais gostava, cortava-os em pedacinhos que introduzia em minha boca – derramando sentidas lágrimas cuja razão, francamente, eu não percebia. Deves chorar por meu pai – eu dizia – que está morto, por minha mãe que está morta, por meu irmão mais velho que está morto; mas choras por mim. Por quê? Escapei com vida de uma explosão que teria liquidado qualquer um; não preciso mais trabalhar; cuidas de mim com desvelo; de que devo me queixar?
Cedo descobri. Ao visitar certa modista.
Esta senhora, uma viúva recatada mas ardente, me recebia todos os sábados, dia em que os filhos estavam fora. Quando me senti suficientemente forte telefonei explicando minha prolongada ausência e marcamos um encontro.
Ao me ver ficou, como era de se esperar, consternada. Vais te acostumar, eu disse, e propus irmos para a cama. Me amava, e concordou. Logo me deparei com uma dificuldade: o coto (assim eu chamava o que tinha me sobrado da mão esquerda) e a pinça (os dois dedos restantes da direita) não me forneciam o necessário apoio. O coto, particularmente, tinha uma certa tendência a resvalar pelo corpo coberto de suor da pobre mulher. Seus olhos se arregalavam; quanto mais apavorada ficava, mais suava e mais o coto escorregava.
Sou engenhoso. Trabalhando com técnicos e cientistas aprendi muita coisa, de modo que logo resolvi o problema: com uma tesoura, fiz duas incisões no colchão. Ali ancorei coto e pinça. Pude assim amá-la, e bem.
– Não aguentava mais – confessei, depois. – Seis meses no seco!
Não me respondeu. Chorava. – Vais me perdoar, Armando – disse – eu gosto de ti, eu te amo, mas não suporto te ver assim. Peço-te, amor, que não me procures mais.
– E quem vai me atender daqui por diante? – perguntei, ultrajado.
Mas ela já estava chorando de novo. Levantei-me e saí. Não foi nessa ocasião, contudo, que fiquei deprimido. Foi mais tarde; exatamente uma semana depois.
[...]
(SCLIAR, Moacyr. Melhores contos. Seleção de
Regina Zilbermann. São Paulo: Global, 2003. p.
176-177.)

 Conheça nossos planos