Questões de Vestibular
Comentadas sobre interpretação de texto | reading comprehension em inglês
Foram encontradas 2.309 questões


Disponível em: <http://www.goodreads.com/quotes/281078-don-t-be-in-a-hurry-to-condemn-becausehe-doesn-t>. Acesso em: 12 set. 2016
Citações são passagens curtas retiradas de textos orais ou escritos. Nessa citação, Malcolm X aconselha a:

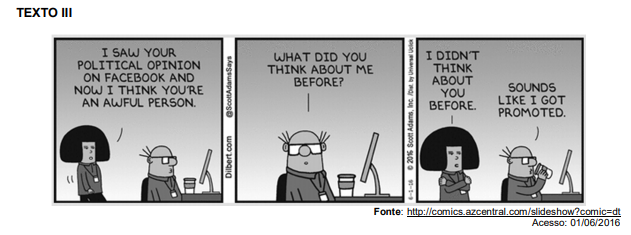
No diálogo da tirinha,
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)
Read the following passage, paying attention to the words numbered 1-5
Gene Wilder’s passing away, the eternal Willy Wonka
After analyzing items I-V, check the CORRECT option.
Published in 1981, Todd Strasser’s The Wave recounts a true incident that took place in a history class at a Palo Alto, California, high school in 1969. The teacher of the class, Ron Jones, (1)__________ is fictionally renamed Ben Ross in the book, actually formulated the experiment described in the narrative in an effort to help his students understand how the Holocaust could have happened without the mass condemnation of the German people. What begins as a simple class project quickly takes on a life of its own, (2) __________, as students conform mindlessly to the experimental system, and others are pressured ruthlessly to join in. Group dynamics and peer influence bordering on coercion create a sinister atmosphere of fear and mistrust, The Wave spontaneously takes on the characteristics of a cult. The event disrupts an entire school (3) __________ raises a plethora of dark questions concerning responsibility, freedom, and group dynamics. Ron Jones calls it “one of the most frightening events ever experienced in the classroom.” As a novelization of a teleplay by Johnny Dawkins, based on a short story by Ron Jones, Strasser’s book (4) __________ not have attracted an abundance of criticism as a literary entity in itself, (5) __________ The Wave clearly holds an important place in the canon of young adult literature. (…) Available at: <http://www.enotes.com/topics/the-wave/critical-essays>. Accessed on: 20 set. 2016
Choose the CORRECT alternative..

 Conheça nossos planos