Questões de Vestibular Comentadas sobre inglês
Foram encontradas 2.807 questões


Leia o texto 12 para responder à questão.
TEXTO 12
I, too, sing America.
I am the darker brother.
They send me to eat in the kitchen
When company comes,
But I laugh,
And eat well,
And grow strong.
Tomorrow,
I'll be at the table
When company comes.
Nobody'll dare
Say to me,
"Eat in the kitchen,"
Then.
Besides,
They'll see how beautiful I am
And be ashamed--
I, too, am America.
Poem by Langston Hughes
Disponível em:<http://www.poemhunter.com/poem/in-time-of-silver-rain-2/#content>
Na música Another Brick on the Wall da banda inglesa Pink Floyd, a dupla negativa é usada como crítica ao severo sistema educacional inglês em:
Nelson Mandela Disponível em:<www.brainyquote.com/quotes/authors/n/nelson_mandela.htm>. Acesso em: 24 ago. 2016
Nelson Mandela foi um líder rebelde, presidente da África do Sul de 1994 a 1999 e agraciado com o prêmio Nobel da paz em 1993. Nesse trecho, Mandela diz que nenhum de nós pode verdadeiramente descansar enquanto persistirem:
Leia o texto 11 para responder à questão.
TEXTO 11
WORLD THAILAND
Thailand Is Growing Concerned That Zika May Start to Impact Tourism Thai Health officials have expressed fears that the Zika virus will have a negative impact on the country’s booming tourism industry. “If we say which province has infections [of Zika] then attention will turn on that province, and if that province is popular with tourists it will have an impact on tourism,” Anuttarasakdi Ratchatatat, an epidemiologist at the health ministry’s Bureau of Vector Borne Disease, told Reuters,
There have been 100 confirmed cases in Thailand since January. Twenty-two new cases of Zika were confirmed in Bangkok alone last Sunday.
Thai authorities also reported monitoring 30 pregnant women infected by the mosquito-borne virus. The health ministry told Reuters six women have given birth without complications so far.
Samlee Pliangbangchang, former regional director of WHO’s Southeast Asia office told Reuters, “We don’t know the extent of the Zika spread in Thailand.”
However, recent maps by the European Centre for Disease Prevention and Control (ECDPC) suggests “increasing or widespread transmission” of the virus in the country, which, with its tropical climate and rainfall, provides ideal breeding grounds for mosquitoes.
Thailand welcomed nearly 30 million visitors in 2015, making it one of the world’s top destinations.
Disponível em:<http://time.com/4487130/zika-thailand-tourism-concerns/?xid=homepage>
Disponível em: <http://www.goodreads.com/quotes/281078-don-t-be-in-a-hurry-to-condemn-becausehe-doesn-t>. Acesso em: 12 set. 2016
Citações são passagens curtas retiradas de textos orais ou escritos. Nessa citação, Malcolm X aconselha a:

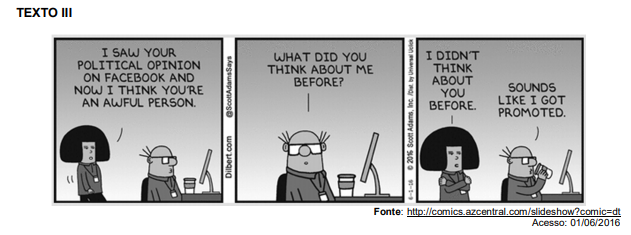
No diálogo da tirinha,
Leia o texto para responder a questão.
Patience is needed for Brazil to come good again
Michael Hasenstab
Dr. Michael Hasenstab is executive
vice-president, portfolio manager
and chief investment officer of
Templeton Global Macro
The Olympic Games in Rio drew global interest to Brazil, but the country and the rest of South America has been in sharp focus for investors all year. They have flocked to the region as part of a broader migration into emerging market debt, following record low valuations and the hunt for yield in a low interest rate environment. While investors have been presented with a rarely seen buying opportunity in emerging markets like South America, it is a mistake to regard these countries as a homogenous group.
That leaves the challenge of working out which are the most attractive opportunities – some of our best known investments were not obvious choices.
We have devised a formula to help us evaluate the fundamental strength of different emerging market countries. It scores a country’s current and projected strength on five factors: how well it has learnt the lessons from past crises; the quality of its policy mix; the structural reform being undertaken to boost productivity; the level of domestic demand; and its ability to resist external shocks. The aim is to pick nations that are fundamentally strong but, for one reason or another, are out of favour with investors. It can take time for the market to catch up to reality. But if you are a long-term investor – and we are certainly in that camp – you have the luxury of being able to wait.
Brazil, for example, is known as a vulnerable market due to the commodities downturn, the ongoing corruption crisis and ensuing political turmoil, but our work suggests to us that it is poised for a potentially significant rebound in the long term. Its current score is low, but its projected future score tells a different story.
We believe the country has learnt the lessons from the most recent crisis, which brought home the importance of having a sustainable fiscal policy. It has already adopted a flexible exchange rate, has strong foreign exchange reserves and has limited short-term debt. This is also reflected in the country’s improving resilience to external shocks, with a reliance on commodities, at 60 per cent of exports, being the largest remaining negative.
It is perhaps no surprise, given Brazil’s deep recession and political instability, that there is much work required in terms of improving policy mix, making structural reforms and boosting domestic demand. However, there are signs things are being turned around, with monetary policy already being tightened aggressively to bring inflation expectations back under control, and the previously excessive levels of governmentsubsidised lending being cut. Once political stability returns, the government will be empowered to do even more.
Work on structural reform should accelerate too, as Brazil’s middle class has made it clear it wants greater transparency and an economic policy framework that can both boost living standards and improve the environment for businesses.
(www.ft.com. 01.09.2016. Adaptado)

 Conheça nossos planos